Showing posts with label geithner. Show all posts

Wednesday, March 31, 2010

We're all rich


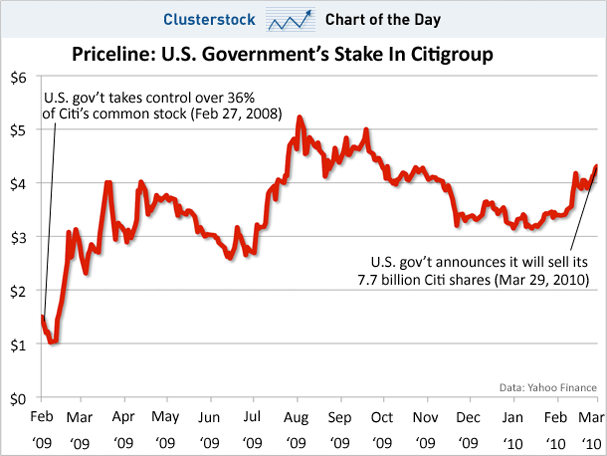
Via Clusterstock comes this look at how the US Government is set to make around an $8 billion smackeroos profit off the "bailout" of Citigroup. In fact it's also conceivable that we'll break even on our "investment" in AIG.

So if the net profit off both AIG and Citigroups is $8 billion... divided by... carry the one... each American stand to make $26 off the bailouts. Excuse me, $26 dollars... and five cents. Oh yeah baby, we're rich. "Going to the movies with a date and getting a small popcorn" rich! Which, comparatively, is like "owning a sports team" rich was before the economy had its throat slit.

So sit by the mailbox, I'm sure that as soon as Geithner finalizes these sales you'll have your motherfuckin' movie check sent out to you, post haste.

The entire economy collapses and we all get $26? I told you this would all work out in the end.

Tuesday, February 16, 2010

Exciting economic news!

Just when you thought the economy was surging to new heights and you'd finally be able to place an order for the platinum monocle, top hat, and spats you'll need as part of your wardrobe now that everyone has ascended to the top of the gilded class what with all these great new jobs we all got... think again. You know the drill; unending horror, plague of locusts, fire from the sky.

But at least it's a different kind of fire. Sure, it's mortgage failures, but on commercial real estate! Oooh, total curveball. And yes, it will imperil society, destroy small businesses, and hinder the economic recovery. Excuse me, economic "recovery." Why do you know you should be afraid? Because the warning are coming from Elizabeth Warren's Congressional Oversight Panel.
A huge wave of mortgage failures on commercial real estate could hit next year, causing banks to lose as much as $300 billion, imperiling lending for small businesses and hindering the economic recovery, a Congressional panel is warning.

In a report to be released on Thursday, the Congressional Oversight Panel... said commercial loan losses could jeopardize the stability of many banks, particularly the nation’s midsize and smaller banks, contributing to prolonged weakness throughout the economy.

The panel’s chairwoman, Elizabeth Warren, has been pressing the Treasury to compel thousands of banks to undergo stress tests like the ones that the Federal Reserve required of 19 of the country’s biggest financial institutions early last year. The Treasury secretary, Timothy F. Geithner, has called that idea impractical.
The signs are there: Elizabeth Warren saying something bad is on the horizon and coming up with a solution to head it off, Tim Geithner shrugging off the advice and the warning, and industry spokeswhores and lobbyists from organizations such as the Commercial Mortgage Securities Association and the Independent Community Bankers Association calling the reports and warnings exaggerated while touting the overall health and rock solid stability of the nation's banks.

I think we all know what that means: further economic collapse followed by complete societal destabilization and cannibalism. I've learned not to go against Warren when flesh reaving is on the line. So there are two options here: get used to the taste of human jerky or wait for Congress and the rest of our elected betters to act. I think we know how that's going to go. I'll get the teriyaki marinade and you get the meat smoker, I smell further banking collapse on the horizon. And mesquite smoke.

Monday, January 25, 2010

Asshole advocates for asshole

With the confirmation of Ben Bernanke seeming to take a happy little detour into the bottomless canyon of failure that is the United States Senate, a stifled yawn and cries of "No really, that's a shame, awwwwwwww" are coming up from most casual observers and critics of the Fed Chairman. Mostly that stems from the fact that he either completely failed to see or completely failed to act on the large housing bubble, seems intent on ignoring his mandate to attempt to get this country to full employment, and that his sole claim to fame as Fed Chairman seems to be that he hasn't fucked up during this recession. Which, seeing as how things are still shitty, isn't much of an endorsement.

But there are people coming to Ben's defense. It's just a shame it's another guy everyone thinks is fucking up.
Treasury Secretary Timothy Geithner warned that the financial markets would view a Senate rejection of Ben Bernanke's renomination as "very troubling" but said he's sure the embattled Federal Reserve chairman will prevail.
...
"He's done a remarkable job of helping steer this economy out of the great recession. And I think he'll play a very important role in helping in the success of our efforts to try to make sure we are bringing this economy back to durable growth."

Asked about possible market reaction to a defeat, Geithner said: "I think the markets would view that as a very troubling thing to the economy as a whole."
First off? This country: not steered out of a recession. Point of fact: still in recession. Point of other fact: looks to be in recession for foreseeable future. Second point: country is not being brought back to durable growth.

And threats of a Wall Street tantrum, also echoed in this Washington Post editorial that echoes the same line of bullshit Geithner is slinging? Well I imagine they would be pretty pissed off if a guy who has been looking out for them and only them was suddenly out of a job, but I'm not that concerned about their feelings. I have this bizarre idea that the economy isn't some GDP number or stock market number; that the economy is about the relative financial health and stability of the people in the economy.

Now I know when Bernanke was made our Infallible Money Jesus he, like those who came before him, ceased to be a mere mortal as his brain became attuned to what our financial Gods wanted and his proclamations became unerring law. But people seem to look at the results of his tenure, not like what they see, and want a guy who was, you know, ahead of the curve and maybe interested in their problems. 10% unemployment does irrational things like that. It's this foreign concept some refer to as "holding people responsible for their performance." We don't do it too often with financial leaders, so I can see why it's such a shock it might be happening to Benny.

I know it's hard to understand, but there was a time in this country when Ben Bernanke wasn't the head of the Fed. Time still flowed forwards and the fabric of the universe was still held together. I'm just saying I think it might be possible, nay probable, that the universe won't compress itself into a singularity if Ben Bernanke has to return to Princeton and he gets replaced by someone who gives a fuck about things that aren't massively giant financial corporations. But, then again, I've been wrong before.
Friday, January 22, 2010

Awwww

Senate Dems Not Sure They Can Get Enough Votes to Reconfirm Bernanke
Amidst the voter anger at Wall Street and Washington, D.C., ABC News has learned that the Senate Democratic leadership isn't sure there are enough votes to re-confirm Ben Bernanke for another term as chairman of the Federal Reserve.

Bernanke's term expires on Jan. 31.
What a shame. I just can't believe that in this day an age an ostensible agent of government who feels it is his duty to look out for financial and banking giants at the expense of people, completely neglects the bolded large print declaration that the central bank is supposed to be committed to enacting polices that promote full employment, tilts at windmills and the imaginary dragons of inflation, presided over a disaster, did nothing to stop it or foresee it, and is unpopular with the American people, isn't finding much support in Congress.

As an added bonus, it seems that Geithner is on the outs as well. Hey, I guess better late than never. Sad that it has to take months and months of deeply unpopular toadying to the people who ruined the economy before someone speaks up and says "Maybe... this is a... bad... idea?" while someone else tentatively nods in agreement. Or as Matt Taibbi puts it "the government only starts listening to its voters once the more corrupt option turns out to be untenable."

So soon we might have a new head of the FED and, if Obama seems to be moving away from his ideas, a new head of the Treasury. Hah! Just kidding. Did you see the confirmation rate in the Senate for Presidential appointees? Even if he dumps the both of them, it'll be years before both positions were filled. I'm not sure if those would be bad things at this point, but that's where we are. That is unless Senate Democrats are able to muster some sort of unified and bipartisan support for something supported by the President. LOLersaktes!

So sorry Ben. Bitches will eventually know about your rate cuts and we all appreciate your rocket cycle heroics, but we just can't let you run things anymore. I guess it's back to Princeton to boss around Krugman. That might be as fun as swimming in the Fed's money vault. Fare thee well.

Tuesday, November 17, 2009

Your window into the sense of entitlement of our financial betters

From a New York Times article on the TARP inspector general Neil Barofsky's scathing report on the decision to pay off AIG's creditors in full.
Just two days before the New York Fed paid A.I.G.’s partners 100 cents on the dollar to tear up their contracts with the insurance giant, one bank volunteered to take a modest haircut — but it never got the chance.

UBS, of Switzerland, alone offered to give a break to the New York Fed in the negotiations last November over how to keep A.I.G. from toppling and taking other banks down with it. It would have accepted 98 cents on the dollar.

But UBS’s good-faith gesture was quickly drowned out by Goldman Sachs and the top French bank regulator. They argued, with others, that it would be improper and perhaps even criminal to force A.I.G.’s trading partners to bear losses outside of bankruptcy court.
Those are some balls on display. First by UBS, agreeing to take 98 cents on the dollar instead of 100 cents and pretending it is some grand compromise when their assets were worth 40 cents on the dollar, and then by Goldman-Sachs, who claimed that it would be illegal if they didn't get all their money in full. Thankfully they all got every penny that was owed to them. Why? Because Tim Geithner knows how to treat his old bosses. Is there a position higher than Treasury Secretary we can put him in?

What's it that Taibbi said about Goldman-Sachs? "The world’s most powerful investment bank is a great vampire squid wrapped around the face of humanity, relentlessly jamming its blood funnel into anything that smells like money"? He was being too kind.

Friday, November 13, 2009

Stay classy, Feds

Quick question: how do you stop the fucking peasants who deign to catch a glimpse of the unelected betters who cart dump trucks full of money to our financial betters on Wall Street? By changing them exorbitant sums of money for their pissant Freedom Of Information Act requests.
The Treasury Department wants more than $500,000 to comply with a Freedom of Information Act request, a fee an attorney on the case suggested Tuesday might be one of the largest bills of its kind.

“I have not seen one that has been larger,” said Noah Wood, a Missouri attorney suing the government to comply with his nearly four-year-old FOIA request.

The Treasury Department, Wood said, is “downright telling us where we can stick it.”
...
Still, the government wants Wood to pay $522,886 for the records. The original tab was more than $26,000, but after some revisions in what Wood was seeking, the government upped the ante — even though not all information sought would be forthcoming, according to the bill (.pdf).

How else is the Treasury going to recoup all that money it handed out to banks? By asking them to pay it back? You're fucking out of your mind.

Sadly this man wasn't trying to get information about the bank bailouts. No, that would have been almost too perfect. No, the man in question was simply trying to get info about some sort of deal with the Libyans and unpaid monies. I think it involved plutonium and a fake bomb made out of pinball machine parts. But hey, you gotta appreciate any attempt the Treasury Department takes to make itself even more lovable than it already is. Half a mil for making copies. Time Geithner can't keep the lights on charging 3 cents a page like Kinko's. Stay classy, Treasury Department.

And for God's sake if Matt Taibbi ever makes an FOIA request to you, please try to charge him half a million. The world needs another one of his articles on the financial industry and needs it to be completely filled to brim with utter disdain and bile.

Wednesday, October 28, 2009

Cheap Blogging Crutch 10.28

Fox-Friendly Poll on Imaginary White House Policies
From Fairness and Accuracy in Reporting comes a report of a dandy of a poll from Fox News and Zogby whereupon they ask the question if Americans think that Obama's communist diversity czar's imaginary desire to force out the "good white people" in the broadcast industry to make room for the blacks and the gays and the gay blacks represents a threat to free speech. Nothing like a little conspiratorial race bait push polling to start your day. Gee, I wonder why it is that the Obama Administration doesn't like Fox News?

Analysis: Public Option Is Likely Popular in Most Blue Dog Districts
Nate Silver of 538 works his number witchcraft to look at the popularity of the public option....in every single congressional district. The conclusion? That the public option has support in almost 2/3rds of all districts and in regards to the biggest Democratic gainsayers, the Blue Dog caucus, the public option holds majority support in 34 of 52 of their districts. The conclusion supposedly being that a public option should have more support of our elected betters. Ahh Nate, your cold robot logic has failed you again. Don't you know no one in Congress actually cares about what its constituents thinks? But we do appreciate you giving us yet another mathematically valid reason to hate everyone in Congress.

New York Fed’s Secret Choice to Pay for Swaps Hits Taxpayers
Pop quiz: how do you get AIG to look good? Answer: Make sure they're being compared to Tim Geithner. That's right our beloved Treasury Secretary Timmy demanded that the US government pay AIG 100 cents on the dollar for their utterly worthless credit default swaps when AIG was only seeking to get 40 cents on the dollar for them. This cost taxpayers and additional $13 billion dollars. The kicker? This allowed AIG to pay back the $14 billion it owed to Timbo's former employer Goldman-Sachs. Next time Tim, can you put on some cowboy gear, cover your face with a black bandanna, tell us "to reach for the sky", and make us pile the money into a burlap sack with a dollar sign on it? If we're going to get robbed, can we at least get to appreciate the theatre of it?

Losing Net Neutrality: The Worst Case Scenario
Gizmodo links to a half satirical/half terrifying representation of what kind of internet deal we'll be getting from cable companies if Congress votes to ditch net neutrality. Why wouldn't we want our internet priced out and divided up like cable channels, everyone loves how that works, don't they?

LHC Reawakens, Sending Proton Beams Running at the Speed of Light
Finally the scientific community gets off its lazy, goldbricking asses and starts trying to kill God in earnest again. They've fixed the helium leak, stopped the problem they've had with magnets overheating, scrapped plans to convert the LHC into a pussy magnet, and found that missing pallet of particles that idiot Jenkins misplaced. Hopefully within the next few months God will be dead or the French/Swiss border will find it has a new black hole taking up residence and consuming our solar system. Just get it over with, it's not like any of us have jobs or anything to live for.

Thursday, July 23, 2009

Cheap Blogging Crutch 07.23

Make no little plans
The epic tale of NYU President John Sexton and his multi-billion dollar quest to make New York University the premier academic institution in the world....by building a branch campus to teach western style education in the heart of a repressive regime not known for intellectual freedom, respect for individual rights, and a religious based Islamic education foundation. I'm sure there will be no problems with all that. Still, the NYU-Abu Dhabi campus is not as illustrious as the branch campuses my alma mater, Pitt, has in Greensburg or Titusville, but it'll do. I think ole Johnny Sexton is going to be blown away by our multi-thousand dollar facility that's under discussion for Kittaning.

Ignoring Watchdog Report, Treasury Gives Three Major Banks Sweetheart Deals
SO it turns out that Tim Geithner might just be a total financial industry suck-up and goon? My faith in the best and brightest of Wall Street is shaken once again. Sweetheart deals for banks? Taxpayers only getting 2/3rd's of the value of its assets? Nude old white man orgies on piles of greasy money? Funnily enough the one bank that did pay fair market price for the warrants was Goldmann-Sachs, probably out of fear. Score one for Matt Taibbi. See, sometimes when you yell at a company looting the American taxpayer, you can startle them so badly that they drop a few nickels.

Leader Of GOP Health Care “Solutions Group” Says GOP Won’t Offer Health Care Bill

What? You're telling me the GOP doesn't have a health care solution beyond "vaguely endorse things being cheaper" and then stamping their feet, holding their breath and yelling "Socialism!" at anything that attempts to make things cheaper? Shocking.

New York Times Reports $39.1 Million 2Q Profit
Somehow, possibly through witchcraft or some other dark art, a newspaper made money. I can only assume that this is because the Times was able to reclassify itself as a bank and get bailed out. I think that's how they were able to negotiate the selling off of a bad asset like Bill Kristol back to the conservative movement.

Obama, Farm Industry Clash Over Antibiotics
It seems that President Obama and the FDA have decided that maybe the food industry pumping every animal full of antibiotics, us eating those drugged up animals, and resulting creation of super-drug resistant bacteria, isn't such a great idea. They've proposed a bill to make it illegal to give new antibiotics to farm animals unless they're actually sick and restrict the use of older form of the drugs. Because this makes sense and is supported by scientific research, it will have trouble getting passed in the Senate. For a greater understanding of why this is all bad, go see Food Inc., and then be driven to never eat anything again.

Tuesday, April 21, 2009

No take backsies

Geithner: No new bailout money needed
The U.S. Treasury still has about $134.6 billion available in its coffers from last fall’s bank bailout package and that should be enough for it to avoid asking Congress for more money, Treasury Secretary Timothy Geithner said Tuesday.

“We have the resources to move forward implementing all aspects of our Financial Stability Plan,” Geithner said in a letter to the panel overseeing the bailout.

Geithner will face a slew of questions Tuesday morning about his plans to shore up banks. He is scheduled to testify before the Congressional Oversight Panel for the government’s $700 billion financial rescue program, while a watchdog agency warns that Obama administration initiatives could increasingly expose taxpayers to losses.
Promise? We all heard him, right? No new money needed. He can't take that back, we have witnesses. I don't care if his fingers were crossed, the banks will just have to make due with the trillions they've already gotten.

It is nice to know that Timmy thinks we won't need to pass another multi-billion bailout package for people who seem to get physically ill at the thought of having the government looking over their shoulder as it makes them fiscally solvent. On the other hand, there is a report from a independent watchdog group that says the way the bailouts are structured leaves the taxpayer vulnerable to losses. That is surprising, who would have ever guessed that attempting to remove any shred of risk to investors and companies in an attempt to get worthless assets off the books would end up exposing taxpayers to more risk? Everyone or just everyone who heard the plan?

The report from TARP Inspector General Neil Barofsky, who just opened 20 criminal probes and six audits into how the money was spent, offered up a 250 page report on how things were going, ways things could be made better, and how he wishes the Treasury Department would listen. Among those suggestions: new "conflict of interest" rules, disclosure of private equity stakes in funds, "investor screening" programs to prevent money laundering, and exasperated cries for people to start listening to watchdogs and implementing their suggestions. In his defense, Mr. Barofsky only used three instances of the word "unfuckingbelievable", two exasperated cries of "Is anyone listening to me", and tried really hard to write the report in a tone that suggested that he thought Tim Geithner was actually going to read it and consider his smart ideas. Oh well Neil, maybe next bailout.

Wednesday, April 8, 2009

Difference of opinion

The Congressional Oversight Panel, who you might recognize as the panel that, despite a legal requirement to do so, no one in the Treasury Department, FED, Wall Street has deemed worthy enough to update as to the goings on and payments made out in the various bailouts and free cash grabs, had a few choice words on the plans enacted so far.
A congressional panel overseeing the U.S. financial rescue suggested that getting rid of top executives and liquidating problem banks may be a better way to solve the economic crisis.

The Congressional Oversight Panel, in a report released yesterday, also said the Treasury may be relying on too rosy an economic scenario to guide its $700 billion bailout, and declared that the success of the program after six months is “mixed.” Three of the group’s members disagreed with at least some of the findings.

“All successful efforts to address bank crises have involved the combination of moving aside failed management and getting control of the process of valuing bank balance sheets,” the panel, headed by Harvard Law School Professor Elizabeth Warren, said in its report.
Tim Geithner responded by screaming and pointing at a bear that he not only swore was totally behind the press and about to eat them all unless they ran, but that the press had to hire the bear on as a consultant so the bear could advise them on how not to get eaten by a bear.

Hey isn't it funny how the one government organization that doesn't have Wall Street insiders, Goldmann Sachs money fuckers, or political hacks that greased the skids for this crisis and is staffed by economists and number crunchers is the one advocating a fire and liquidate approach? Sorry, I wrote 'funny' when I meant to write 'a blindingly obvious result'.

But the report did also mention that things were getting better, albeit too slowly and in a 'not effective enough' manner. Perhaps the fact that things are getting a little better, combined with positive public perceptions of the status of the economy mean that good things...wait, no, Paul Krugman just dropped in to defecate on that notion in a Nobel laureate kind of way and sup on the sweet tears of your ignorance.


Oh lovely, 'things are terrible, but the speed at which things are getting worse has slowed, which is sort of good' is the most positive thing he can say. Yeah.....I'm going to go drink.

Thursday, March 26, 2009

New finance rules

Today the Obama Administration unveils their new financial plans. Not just content to attach strings after the fact to billions they've handed out freely, Tim Geithner and the other three people working at the Treasury Department have decided to come up with a plan to address new regulation of the financial markets to help better avoid a future financial Ragnarok. The sooner the better as the canvas bubble fueled by the tent cities springing up around the US will threaten the economy in 2011.
The plan, which would require Congressional approval, would give the government vast new powers over “systemically important” banks and other financial institutions that are so big that their collapse would jeopardize the economy as a whole.
...
If regulators decided that a company had become “too big to fail,” as was the case with A.I.G. in September, they would subject it to much stricter capital requirements than smaller rivals and much closer scrutiny of its borrowing levels and its trading partners, or counterparties.

But the most striking new proposals, and the ones that may provoke the most heated opposition from the industry, would regulate so-called private pools of capital — hedge funds, private equity funds and venture capital funds — and the gigantic market in financial derivatives, including instruments like credit-default swaps, the insurancelike instruments that allow investors to hedge against bond defaults.
Of course this has to pass Congress, so there's a 50/50 chance that Harry Reid will have to water the bill down to the point where it actually deregulates the markets further just to get Arlen Specter to deign to consider voting for it. Not included in the article was a list of other regulatory measures the bill wishes to take:
  • A company may only engage in enough shady dealings to tank 1/3 of the world economy
  • The bonus system will be completely overhaul...just kidding
  • All senior management must take at least one class on faking sincerity and gratitude
  • ABC will commission the program Extreme Makeover: Corporate Office Edition so as to provide reasonable cover for those corporations still wishing to redecorate during their own collapse
  • Failing companies will only be allowed to have one sports sponsorship at a time and will have to choose between jersey sponsorship and stadium sponsorship
  • When choosing a minority underclass that tricked your company into your economic ruin, all official spokespeople will be allowed only to blame that one group for the duration of the crisis
  • Only 2 handjobs per day for executives at their office spa
  • Horse and dog track betting are now considered legal financial instruments for securities and credit default swaps
  • Monocles, spats, top hats, and canes are mandatory attire for any CEO accepting government bailout funds
  • Senior management must legally pinky swear to never break the economy again

Tuesday, March 24, 2009

Real ultimate power

The White House is expected to send up legislation arguing that Congress should give Tim Geithner more power. Robotic eyes, super speed, metal claw hands, and jaws that crush steel beams. You know, the basic bionic man package. But also some financial powers as well. Because, why not? He's been doing so awesome let's just expand his jurisdiction.
Treasury Secretary Timothy F. Geithner is set to argue for the new powers at a hearing today on Capitol Hill that was scheduled to address the furor over bonuses paid to executives at American International Group, which the government has propped up with about $180 billion in federal aid. Administration officials say the proposed authority would have allowed them to seize AIG last fall and wind down its operations at less cost to taxpayers.

The government at present has the authority to seize only banks.

Giving the Treasury secretary the power to seize a broader range of companies would mark a significant shift from the existing model of financial regulation, which relies on independent agencies that are shielded from the political process.
Normally, I'd say this was a good/great idea. Why shouldn't the government be able to step in and control/quicken the liquidation/fix problems in companies it already ostensibly owns? It already can step in and take over banks, why not financial giants it's shoveling billions into? Yeah, except I doubt they'll ever take over AIG, judging by how they've handled the banks.

Instead of nationalizing banks, we've just concocted scheme after scheme to allow them to go on pretending they hold assets of some value and are financially solvent, most recently last weekend with the unveiling of Geithner's toxic/legacy assets program. They keep drawing the misery out there, stalling action, prolonging the recession, dumping more money in, taking extra bite after extra bite of the shit sandwich instead of one big final one. So why would we expect them to ever do something different with AIG? In the end it'll just be one more thing they drag their feet on.

Monday, March 23, 2009

All you need to know


Today Tim Geithner officially released his toxic legacy assets program. A program which attempts to completely subsidize private investment risk in return for throwing good money after bad in an attempt to pretend excrement is in fact brown gold. A program that was largely derided by economists as trying to pretend the fundamental flaws in the financial system are just superficial, ignoring clear historical precedent and guidance, and one that will prolong our problems and forestall real action.

The Dow responded to this plan by going up 497 points.
The S&P jumped 54.
The Nasdaq went up 98.

Bad economic news is good Wall Street news, as long as Wall Street gets their cut. You really are better off betting your money at the dog track.

The new shitty plan is the old shitty plan

Our new appointed betters at the Treasury Department of One have unveiled their brand new plan to rid financial companies of their toxic assets. Since 'retro' is really in they decided to use Hank Paulson's initial plan, in which everyone in government pretends that all the worthless assets are really worth something and decides to pay what banks wish they assets were worth instead of what their actually worth. That if these assets were priced properly, instead of by loonies who see them as worthless, then all the banks problems are over. One key change: instead of the government buying the toxic crap under the guise of "this is so fucking brilliant" we're gonna get private investors to buy it up.....except we're going to guarantee the assets and end up paying out when it turns out they are, in actuality, just as worthless as everyone thought.
The Obama administration, striving to ease lending in the struggling economy, moved Monday with private investors to sop up bad bank assets. The administration said the program could grow to $1 trillion in purchases eventually, if it proves successful in attacking the bad-books problem that has been at the heart of the banking crisis.
...
To achieve the goal of freeing up more lending, the program would entice private investors with low-cost loans provided by the Federal Deposit Insurance Corporation and the Federal Reserve. The government would also shoulder the vast bulk of the risk.

In one example used in the fact sheet, the purchase of a batch of bad mortgage loans would see the private investor put up 6 percent of the cost with the rest provided by the government, with the FDIC covering 84 percent of the cost with a loan and the remaining 6 percent coming from funds from the $700 billion bailout program.
I know what you're saying, "Didn't this brilliant plan have a name that rhymed so we'd better be able to understand and remember its full implications"? Yes it did, that name was "Cash For Trash". This time it comes with an investor subsidy. Positives? Well if you're into gallows humour, you can enjoy Paul Krugman defecating in anger/despair over the entire concept of the plan and the Obama Administration's handling of the crisis. The world stock markets also rose on the belief that thew government thinks that its just been all one big mistake and that everyone in finance and banking just got a tad overexuberant and is really just as smart and pretty as they think they are.

Other than that......you should probably be moving towards the remotest location you can find so that when society collapses you'll be away from the center of it. Paul Krugman so virulently hating an economic policy means the policy either killed his family and he's been hunting it bent on revenge for years....or it's just a really awful plan. His Nobel isn't in beard grooming, after all. As an added bonus we got to find out that the problem with government response isn't that Republicans hire unrepentant market/banker humpers, its that Democrats hire similar people too....because those are the only people that apparently exist who have any working experience within the Beast. It was so worth extending this recession by another couple years to figure that out.

Monday, March 9, 2009

Broken In Brief: World’s creditors hire mob muscle, demand payment of American debts

ZURICH—Today the creditors, financial institutions and foreign governments of the world, spurred on by the recent economic crisis, demanded that the United States pay it’s nearly $6.5 trillion dollars in outstanding public debt. To show the seriousness of their demands, the consortium announced that they had hired mob muscle to collect the debt and had told them to do so by “any means necessary.”

“It’s time to pay up,” said Heinrich Gellar, spokesman for the group. “The world is tired of funding your continued excesses and we need to start looking out for our own bottom line. We have instructed out friends in the… extra-legal services department... that they are to use whatever methods they can devise to get our money from the collection of destitute gold-brickin' deadbeats you call a 'nation.'”

Already there were reports of bookies and bag men busting up the Washington Monument, but spokesman for the street toughs said it had all been a misunderstanding and that a few of their associates had just gotten clumsy, tripped, and accidentally knocked the beloved structure over. New York made early reports of its storefront windows being broken and there are unconfirmed reports about Wisconsin having its head put in a vise. President Obama and Treasury Secretary Geithner were quick to point out that the country has gone through a bit of a run of bad luck and that if they could just cut them some slack the US would "totally pay them Tuesday and shit." In a press conference to the assembled media, Geithner made several vague allusions to a tip on a horse he had been given.

The mobsters were quick to respond, throwing Georgia out of a moving car and slowly pushing sewing needles underneath Colorado's fingernails. Representatives for the mobsters said that if America didn’t have the money by next week that, “maybe California ain’t gonna look so pretty no more.” Insiders within the White House are quietly hoping Geithner’s bet on the ponies will work out, otherwise Nevada might be forced to trade sexual favors for another extension.

Nobody was even willing to think about what might happen to Ohio, though one mob peon, speaking on condition of fucking anonymity, shrugged and said, "like anyone would notice."

Treasury Department of one

If you had to pick one thing that would be the most terrifying thing you had to hear about the financial crisis, what would it be? That analysts were predicting a barrel of oil would cost more than the entire worth of the Dow Jones Index? That to cut down on resource consumption, feral animals were being loosed into the country to kill citizens at random? That Obama was hightailing it to London to live as President-in-exile until "the worst of the early skirmishes of Civil War II were over"? That the man tasked with planning the fixing of our financial system, administering the bailouts, and creating new regulations was working with a bare bones, skeleton crew department? Good news, only that last one is true.....for now.
In the six weeks since Mr. Geithner took over as Treasury secretary, he and a skeleton crew of unofficial senior advisers have been racing to make decisions that will shape the future of the banking, insurance, housing and automobile industries.

But even as he maintains a frenetic pace — unveiling plans, testifying before Congress and negotiating new bailouts with the likes of Citigroup, General Motors and the American International Group — there are signs that events are getting ahead of him.
...
Compounding the strain on the Treasury, almost all the top posts beneath Mr. Geithner are still vacant. Though he has hired about 50 senior advisers — about half the number he hopes to recruit — the White House has become so worried about potential tax problems and other issues in the backgrounds of candidates that it has nominated only a handful of people.
...
That still left many positions, including the No. 2 post at Treasury, without even a nominee.
That's good, I mean our economy is pretty small an not that complex, so I'm thinking we only need 2-3 guys tops to get a handle on fixing it when it's in a complete tailspin. One to write all the new regulations, one to administer all the money, and one to prepare the suicide pills and write the suicide note to explain to future societies what exactly happened before the economy crumbled.

Worse still, Obama is afraid of bad publicity on tax info to nominate anyone with any speed. Apparently if you're any good at this whole financial game, you're probably also an obvious tax cheat. Why not just push through nominees irrespective of their relative "scandal" status because while fixing the economy, though massively important, might not happen, it might be smart to have a full staff making the attempt? I don't know, either. I think in times like this, not taking a cheap political hit off of manufactured Republican outrage is more important than having a Treasury Department comprised of more than one person.

Friday, February 27, 2009

Tim Geithner calls do-over

Tim Geithner on Wednesday
Nationalization is "the wrong strategy for the country, and I don't think it's a necessary strategy," Geithner said. He added that a government investment in the banks "does not go to pay dividends or excess compensation." He added: "we want the terms designed so that, as conditions normalize, our support is expensive and unattractive," motivating the banks to replace the government support with private sector investment.

Continuing with his views on nationalization, Geithner said, "governments tend to underestimate the scales of problem, they move too slowly, they're too tentative and gradual, they escalate late, and that makes crises deeper."
Tim Geithner today
"We're totally gonna buy up 30%-40% of Citigroup. Nationalization baby, let's have sex in the streets! By the way, has anyone seen that Tim Geithner impersonator that keeps going on TV and saying crazy shit?"
Now I'm sure he's got some legalese and fancified Wall Street word wrangling, but anyone want to explain to me how a government buying 40% of a company, eliminating dividends, and replacing most of the board isn't nationalization? Especially when the move is for a higher risk higher reward move of buying common stock? Not that I'm against nationalization. Krugman is for it and it's what worked in Sweden and eventually in Japan. But it does kind of worry that the guy running things says one thing one day and then decides to do the opposite (or 40% of the opposite) the next day. Doesn't well you up with confidence.

Thursday, February 26, 2009

We need cash...stat!

G.M. Loses $9.6 Billion as Its Struggles Continue
The automaker General Motors said Thursday that its cash reserves were down to $14 billion at the end of 2008, a year when the industry’s worst sales slump in decades nearly forced the company into bankruptcy before the federal government gave it a lifeline.

G.M. lost $30.9 billion, or $53.32 a share, in 2008 and spent $19.2 billion of its cash reserves.

For the fourth quarter, it lost $9.6 billion, or $15.71 a share, as its global sales fell 26 percent. It spent $6.2 billion of its reserves — $2 billion a month — in the fourth quarter alone. The company has said in the past that it needed a minimum of $11 billion to $14 billion in reserves to finance operations, but the estimates were made before the recent drop in auto sales and cuts by G.M. in response.
Wait, people still aren't buying GM cars? Rick Wagoner drove in a hybrid for you ingrates! From Detroit to Washington! He pretended to know what an electric car was! He said hydrogen! Fuel cell! You still have the nerve not to buy his cars? Fine, now he's going to have to reduce himself to begging from Barry even harder. Are you happy now? Has he debased himself enough now?

Luckily he gets to grovel in private this time as today he meets with his new overlords Barry, Timmy Geithner (tax-cheat), and Law-Dog Summers. Rick has already promised to garrote Saturn, Hummer, and Saab, and has commenced pleading with the greedy unions, whose workers make upwards of $700 a second to grab ass with the robots building the cars and organize beer league softball teams, to stop holding them to the deals they signed. Hopefully Barry will deign to have pity on this pitiable CEO, who by the fickle combination of an economic crisis and decades of poor management has been left with only billions in cash reserves and hunks of useless metal cluttering the eyelines of a disinterested buying populace. Let's hope Barry has a couple billions worth of mercy for this poor man.

Tuesday, February 17, 2009

Our financial leaders

If you were one of the litany of people who thought Emperor of Cash Tim Geithner's bank bailout plan was....a tad on the vague side, well it seems there's a perfectly good reason for it: you see he.....LOOK OVER THERE! A SPIDER!
Just days before Treasury Secretary Timothy F. Geithner was scheduled to lay out his much-anticipated plan to deal with the toxic assets imperiling the financial system, he and his team made a sudden about-face.

According to several sources involved in the deliberations, Geithner had come to the conclusion that the strategies he and his team had spent weeks working on were too expensive, too complex and too risky for taxpayers.

They needed an alternative and found it in a previously considered initiative to pair private investments and public loans to try to buy the risky assets and take them off the books of banks. There was one problem: They didn't have enough time to work out many details or consult with others before the plan was supposed to be unveiled.
...
Meanwhile, the sources said, Obama's senior economic advisers were hobbled in crafting the plan by a shortage of personnel. To date, the president has not nominated any assistant secretaries or undersecretaries at the Treasury, and the handful of mid-level staffers who have started work were still finding their offices and getting their building passes and BlackBerrys.
...
But there still was not enough time to sculpt the detailed plan that the financial markets expected. In the end, Geithner and his colleagues decided that it would be better to take flak for being vague than publicly offer half-formed details that might later have to be revised. And ambiguity, the officials concluded, would make the plan an easier sell on Capitol Hill, as congressional leaders could be brought into the discussions of details rather than be presented a detailed plan as fait accompli.
Isn't it nice to see the man in charge of the financial sector bailout described in terms you would usually reserve for a forgetful 9 year old who left his class presentation until the night before, decided to quit because something good was on television, and hoped a furious writing session before first period combined with a litany of vagaries would somehow get him an A?

Furthermore, don't you like the fact that he spent weeks working on proposals that he deemed too risky, expensive, and complex? He had to know that from the start, didn't he? You don't just start work on bailing out an entire industry and then find out at the end it's all really complex and expensive. Then there's the the whole "Everyone's too stupid to understand/we'll tell you about it the day before/watch these rubes get their minds blown by my use of 'fiscal', 'sector', 'depreciation', and 'Keynesian'" tone of the new "We'll Wing It" plan. Not to mention you really gotta love throwing another half a trillion on a plan that got sketched out on a napkin at the bar at a TGI Friday's. This all bodes well for our financial future.

I'm just becoming convinced that everyone working in the financial and banking sectors is at least partially retarded. There aren't a lot of competing theories or evidence to the contrary.